Best Travel Insurance Options for International Trips: How to Choose the Right Coverage
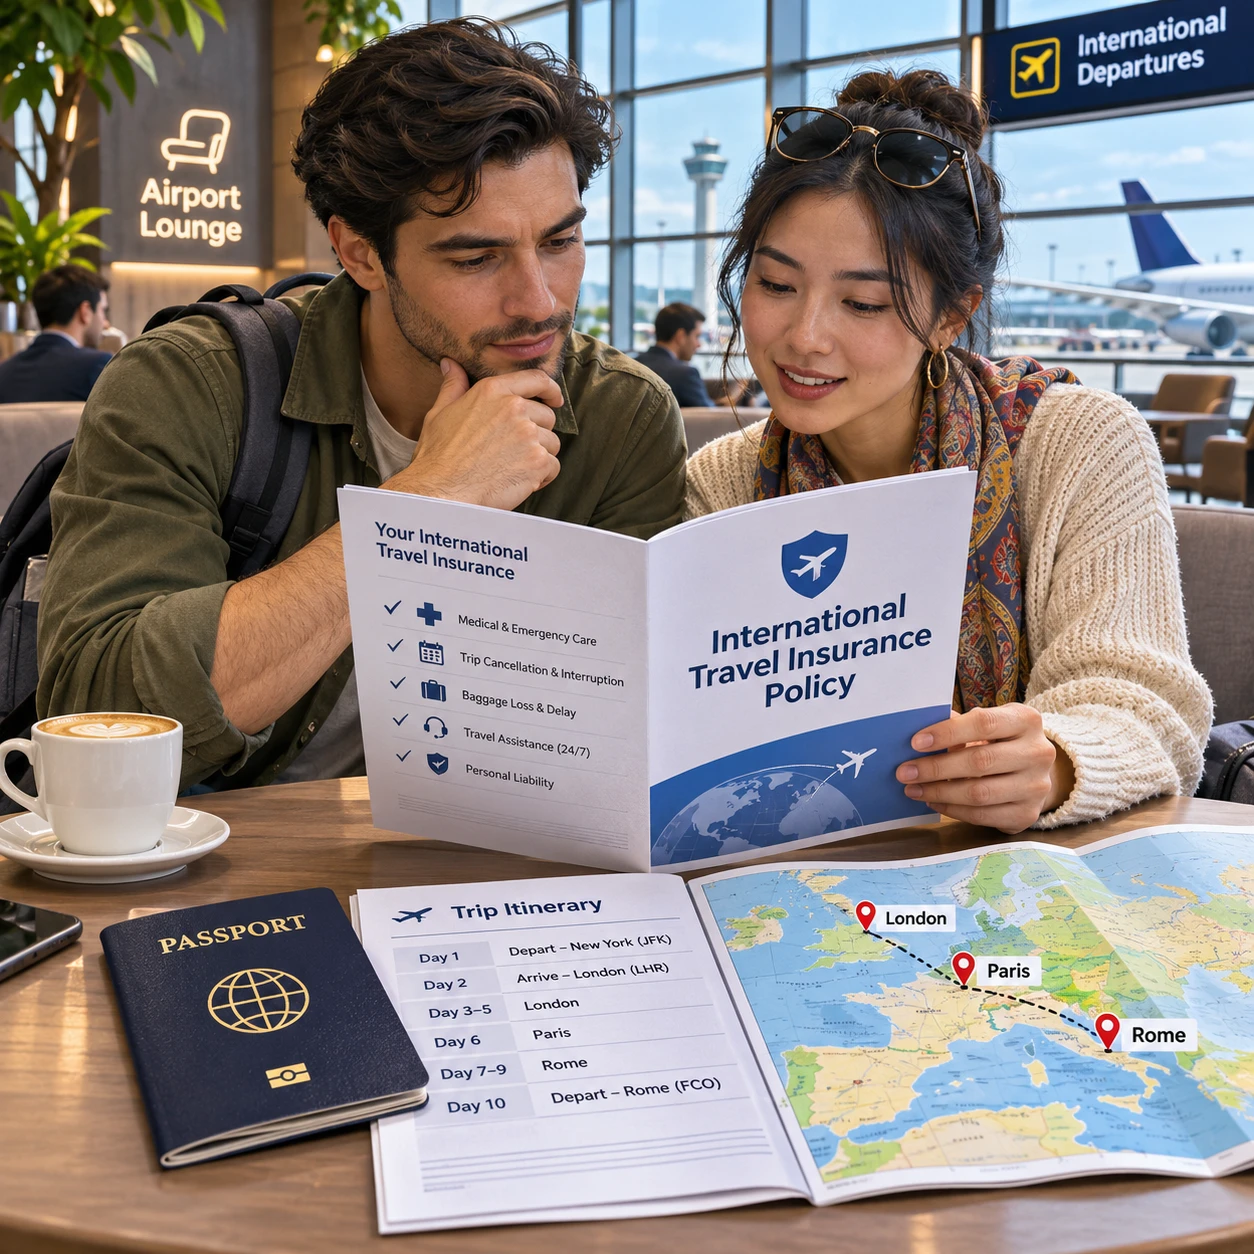
The best travel insurance for an international trip is the policy that matches your destination, health needs, activities, and prepaid costs. There is no universal winner: plans differ in medical coverage, evacuation benefits, cancellation terms, exclusions, and how claims are handled.
Before you buy, check what your tour operator includes, if anything, and compare the actual policy wording rather than relying on a plan’s label. A few minutes spent checking limits and exclusions can reveal gaps that matter once you are abroad.
What international travel insurance can cover
International travel insurance can help pay for eligible emergencies and trip-related losses abroad, depending on the plan. Common benefits include emergency medical coverage, medical evacuation, trip cancellation or interruption, and reimbursement for certain baggage losses or delays.
Emergency medical coverage may help with eligible treatment for a sudden illness or injury during a trip. It does not necessarily cover routine care, every medical condition, or costs above the policy limit. Medical evacuation coverage may pay for transport to an appropriate medical facility, subject to the policy’s terms and authorization rules.
Trip cancellation and interruption benefits may reimburse covered prepaid expenses when a qualifying event forces you to cancel before departure or cut your trip short. Covered reasons are defined in the policy; a change of mind or a situation the insurer excludes may not qualify. Baggage benefits can address eligible loss, theft, damage, or delay, but sublimits may apply to individual items such as electronics.
Benefits vary by insurer and plan. Review the certificate or full policy wording for definitions, coverage limits, deductibles, required documentation, and exclusions. A summary page is useful for comparison, but it is not a substitute for the contract.
Compare the main types of travel insurance
The main options are comprehensive plans, medical-focused plans, and single-trip or multi-trip policies. Choose among them by comparing the risks you need covered, not by assuming one category offers the broadest protection in every situation.
Comprehensive plans
Comprehensive travel insurance usually combines emergency medical benefits with trip cancellation and interruption, baggage protection, and sometimes travel-delay benefits. It can suit travelers with significant nonrefundable bookings who want several types of protection in one policy. The trade-off is that a wider package may cost more, and a listed benefit still has conditions and limits.
Medical-focused plans
Medical-focused cover emphasizes emergency medical treatment and, depending on the plan, medical evacuation. It may fit a traveler whose main concern is medical bills abroad and whose cancellation or baggage risks are limited. Check whether the plan includes evacuation, whether it covers your planned activities, and what it excludes. Do not assume it reimburses prepaid tour costs.
Single-trip and multi-trip options
A single-trip policy generally covers one defined journey. An annual multi-trip policy can be practical for frequent travelers, but it may cap the length of each trip and restrict destinations, activities, or eligibility. Compare the annual premium with the cost and terms of separate policies, especially if one journey is much longer or more demanding than your usual trips.
Which coverage matters for your itinerary?
The coverage that matters most depends on where you are going, how long you will be away, what you plan to do, and how much you have prepaid. Match each likely financial risk to a benefit, then check the limit and exclusions that apply.
- Medical care: Check whether emergency medical coverage applies in every country on your itinerary and whether your existing health insurance offers any protection abroad. Consider the plan’s maximum benefit, deductible, and rules for contacting the assistance service.
- Medical evacuation: Remote areas, cruises, and trips with multiple transfers may make evacuation terms especially relevant. Confirm what counts as a covered evacuation, who chooses the destination, and whether the insurer must approve arrangements in advance.
- Cancellation and interruption: Add up nonrefundable flights, lodging, and tour deposits. Compare that amount with the policy’s trip-cost limit and the covered reasons for cancellation or interruption.
- Baggage and delays: If you carry costly equipment or need essential items on arrival, check per-item limits, proof requirements, and the waiting period for baggage-delay benefits. Keep receipts and document any loss with the carrier when required.
- Activities: Hiking, cycling, diving, and other adventure activities may be restricted or excluded, sometimes based on how they are organized or the altitude involved. Verify each planned activity by name with the insurer.
Trip length also matters. A longer stay can expose you to more opportunities for disruption and may exceed a policy’s maximum trip duration. Health needs require careful attention too: review how the plan defines a pre-existing condition and whether a waiver or other condition applies. Eligibility rules and deadlines vary, so confirm them before purchasing.
How to compare policies and limits
Compare policies by reading the benefit limits, exclusions, deductibles, and claims instructions side by side. The headline price is only useful after you confirm that the plan covers your actual trip and the costs you want to protect.
A simple comparison sheet can keep the decision focused. Record the medical and evacuation maximums, trip cancellation limit, baggage sublimits, deductible, covered activities, and any time-sensitive purchase conditions. Also note whether benefits are per person or per trip and whether other coverage may pay first.
Policy exclusions can be as important as listed benefits. Look for language about pre-existing conditions, unattended baggage, alcohol or drug use, hazardous activities, travel against official restrictions, and known events. Terms differ, so do not assume a familiar phrase has the same meaning across insurers.
Check the claims process before you buy. Find out how to contact the assistance team from abroad, what documents are needed, how quickly you must report an incident, and whether you need prior approval for treatment or evacuation. Save the policy number and emergency contact details offline. If something happens, keep receipts, medical records, carrier reports, and booking confirmations; the insurer will specify what it needs.
For general consumer guidance on travel insurance and questions to ask, see the U.S. Department of State traveler checklist. It is a useful starting point, but your policy wording determines your benefits.
Questions to ask before your tour
Before booking or departing on a tour, ask the operator what is included and compare its answer with your insurance policy. A tour booking does not automatically include travel insurance, and operator protections may cover different risks from an individual policy.
- Does the tour price include any insurance, or must travelers arrange it independently?
- Which activities are included, optional, or operated by a third party, and could any be excluded as adventure activities?
- What are the cancellation, refund, and change terms for the tour, and which prepaid costs would remain nonrefundable?
- Does the itinerary include remote locations, high altitudes, cruises, or border crossings that could affect medical assistance or evacuation?
- What should travelers do if an illness, injury, delay, or baggage problem occurs during the tour?
- Are there booking deadlines or eligibility requirements for the coverage I am considering, particularly for pre-existing conditions or cancellation benefits?
Ask for written answers when a detail affects your decision. Then confirm the insurer’s terms directly; a tour operator can explain its itinerary and booking conditions, but only the insurer can confirm how a policy applies to a particular claim.
Choosing a policy that fits your trip
To choose a policy, map your trip’s costs and risks, identify gaps in existing coverage, and compare plans against those needs. This checklist helps you narrow options without treating any one plan as right for every traveler.
- List your exposure: Note trip dates, destinations, prepaid nonrefundable costs, planned activities, and any remote travel.
- Check existing protection: Ask your health insurer, card issuer, or other provider what benefits apply abroad and request the terms in writing.
- Set suitable limits: Compare medical, evacuation, cancellation, and baggage amounts with your likely costs. A high limit in one category does not make up for a missing benefit in another.
- Read exclusions and conditions: Confirm activity eligibility, pre-existing condition rules, purchase deadlines, deductibles, and required approvals.
- Review support and claims: Make sure you understand how to get help overseas and what evidence you would need to submit.
There is a practical trade-off: broader benefits and higher limits can increase the premium, while a cheaper policy may leave a costly gap. Choose based on the financial loss you could not comfortably absorb and the risks your itinerary actually creates. Store policy details with your travel documents and share emergency contacts with someone at home.
Frequently asked questions
Does standard health insurance cover international travel?
Sometimes, but coverage varies by plan and destination. Ask your health insurer whether overseas emergency treatment is covered, what limits or network rules apply, and whether you must pay upfront. Travel insurance may provide separate benefits, but the policy’s terms determine how they work.
Is emergency medical evacuation included in every policy?
No. Some policies include medical evacuation, while others offer it as an optional benefit or do not provide it. Check the benefit schedule and the rules for arranging and approving transport.
Can I get coverage for pre-existing conditions?
Possibly. Some policies offer a waiver or other coverage subject to eligibility requirements, a purchase window, and conditions such as insuring the full trip cost. Read the definition and confirm your eligibility with the insurer before buying.
Does travel insurance cover cancellations for any reason?
Standard trip cancellation benefits generally apply only to reasons listed in the policy. Some plans offer a separate cancel-for-any-reason option, which may cost more and reimburse only part of eligible expenses if its conditions are met.
Should I buy insurance through a tour operator or independently?
Either route can work. Compare the operator’s offer with independent policies on price, limits, exclusions, activities, and claims support. Confirm what the tour booking itself protects, and avoid assuming that a bundled offer covers medical emergencies or every prepaid expense.